Updated: October 2026 — The Bank of Canada raised its policy rate by a quarter point to 2.5% on October 28, 2026, its first hike since July 2023, and this guide has been updated to match. For what the hike means for condo investors and pre-construction closings, read Bank of Canada Raises Rate to 2.5%: 6 Answers for Condo Investors and Pre-Construction Buyers.
The Bank of Canada raised its policy rate on Wednesday, October 28, 2026, by a quarter point from 2.25% to 2.5%. Prime is expected to rise from 4.45% to 4.70% as the big banks match the move, which lifts the cost of variable mortgages and lines of credit. Fixed mortgage rates had already climbed before the decision because bond yields moved first. For condo buyers and owners, the practical response has not changed: lock in a rate hold if you are buying soon, and check your renewal options early.
Key takeaways
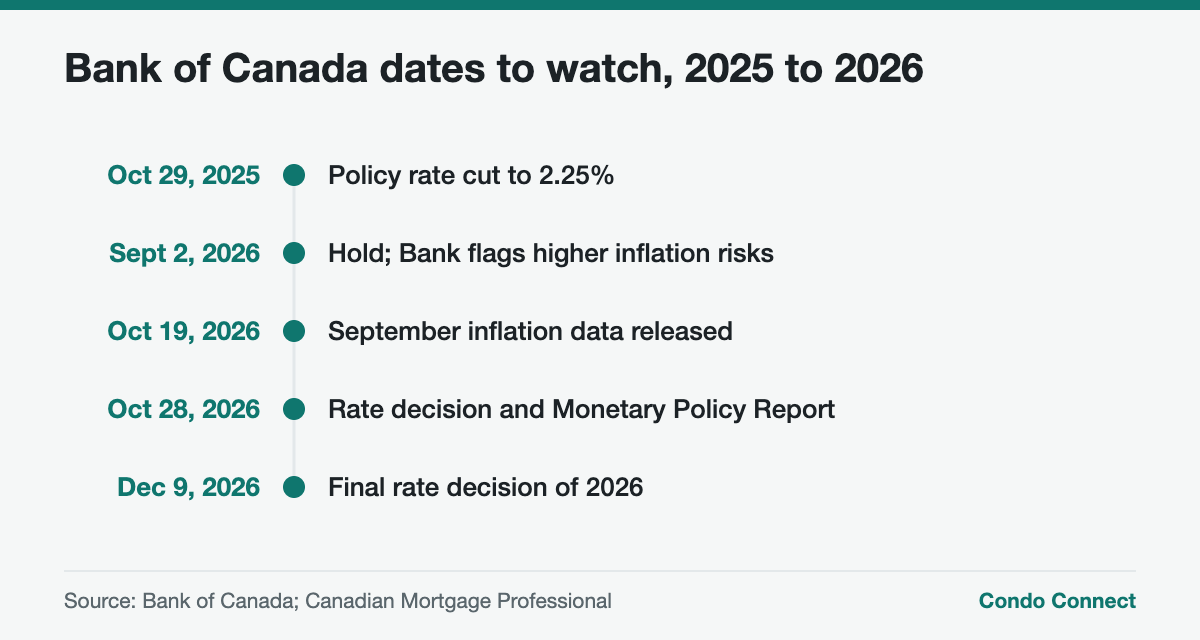
- The policy rate rose to 2.5% on October 28, 2026, after holding at 2.25% since October 29, 2025. Prime is expected to rise from 4.45% to 4.70%.
- After a weak September jobs report, economists surveyed by Canadian Mortgage Professional mostly expected a hold, but the Bank raised rates to keep high energy prices from spreading into other prices.
- The quarter-point hike adds about $60 a month to the payment on a $450,000 variable mortgage.
- Fixed rates track bond yields and rose at all six big banks between September and mid-October.
- Renewing with a new lender on a straight switch does not require a new stress test.
- The Bank says further hikes are possible but it will proceed carefully. The next decision is December 9, 2026.
What happened on October 28?
Update, October 28, 2026: The Bank raised its policy rate to 2.5%, its first increase since July 2023 and its first change since the October 2025 cut. It said the aim was to reduce the risk that continuing high energy prices spread broadly to the prices of other goods and services, and it signalled that more hikes are possible but that it will move carefully. The next decision is December 9, 2026. The background below was written before the decision and is kept for context.
Before this decision, the Bank had held at 2.25% at every 2026 meeting. In September it said upside risks to inflation had increased, which is central-bank language for “we are watching for a reason to raise.” Some analysts said a hike was possible at one of the last two meetings of the year.
The data that followed briefly cooled that talk. Canada lost 68,300 jobs in September and unemployment rose to 6.5%. In a roundup published after that report, five economists largely expected the Bank to hold, and TD’s Andrew Hencic noted markets were pricing about a 27% chance of an October hike. Earlier, in September, economists at RBC and Desjardins had said they expected the Bank to stay put for the rest of 2026 and raise rates in early 2027.
Then the September inflation release on October 19 showed prices up 3.1% from a year earlier, as oil stayed high. The Bank’s October Monetary Policy Report, released with the decision under its 2026 announcement schedule, now expects inflation to rise to about 3.5% by the end of 2026 before returning to 2% in mid-2028.
How the decision changes condo mortgage payments
Only variable-rate mortgages and lines of credit move directly with the Bank’s decision, because they are priced off prime. Before the hike, the best discounted 5-year variable rates were around 3.40% to 3.45%, roughly prime minus 1.0%. With prime expected at 4.70%, those move to about 3.65% to 3.70%.
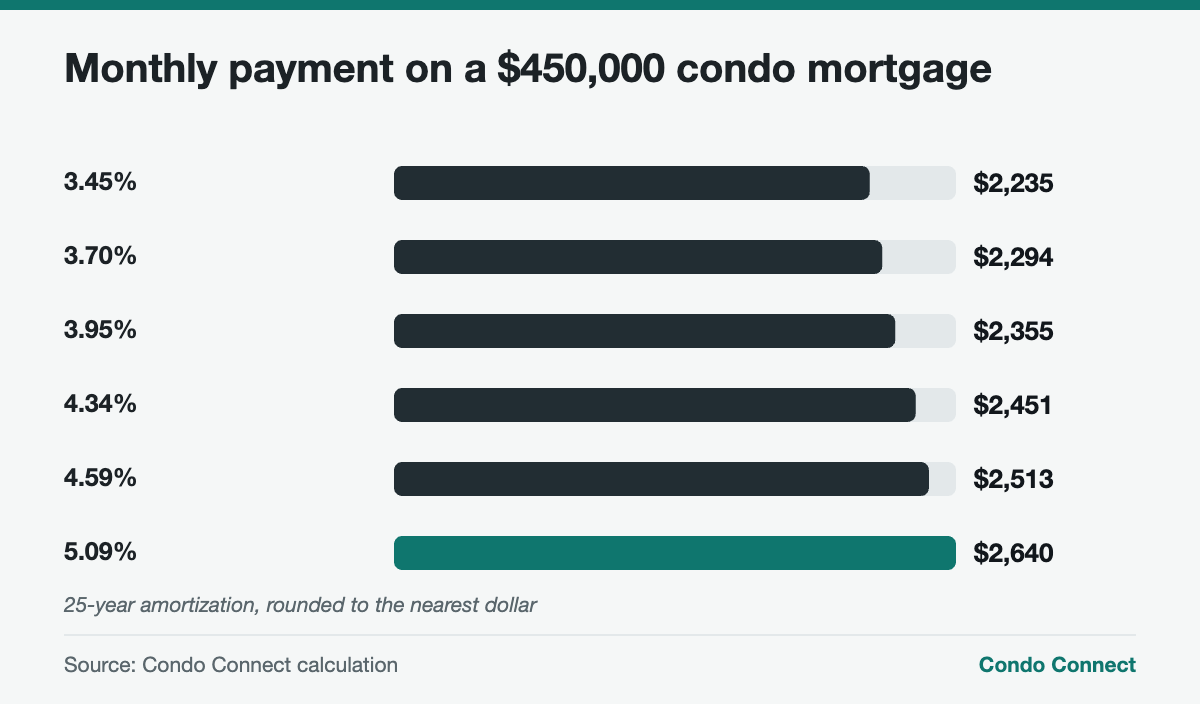
Here is what different rates mean on a $450,000 mortgage, about what you would borrow with 20% down on a $560,000 condo, over 25 years.
| Rate | What it represents | Monthly payment |
|---|---|---|
| 3.45% | Low-end 5-year variable before the hike | $2,235 |
| 3.70% | Low-end variable after the October 28 hike | $2,294 |
| 3.95% | Variable if the Bank hikes again | $2,355 |
| 4.34% | Low-end insured 5-year fixed | $2,451 |
| 4.59% | Typical insured 5-year fixed | $2,513 |
| 5.09% | Typical uninsured 5-year fixed | $2,640 |
Many variable mortgages in Canada have fixed payments, so a hike may first show up as more interest and less principal paid each month rather than a higher payment. Ask your lender which type you have.
Why fixed rates rose before the Bank did anything
Five-year fixed mortgage rates follow the 5-year Government of Canada bond yield, which hit a 52-week high of 3.729% on September 28. All six big banks raised fixed rates between September and mid-October; BMO’s 5-year fixed, for example, went to 5.14% uninsured on October 7.
Comparison sites show the best discounted 5-year fixed rates at about 4.3% to 4.6% for insured mortgages, with uninsured rates higher. The October 28 hike does not change fixed rates directly; what matters for them is where bond yields go next.
Fixed or variable for a condo mortgage right now?
Before the hike, the best variable rate sat roughly 0.9 to 1.2 percentage points below the best insured fixed rate. With variable rates up a quarter point, that gap is now closer to 0.6 to 1 point. A variable rate starts cheaper and benefits if the Bank eventually cuts; a fixed rate protects you if it hikes again.
- Variable suits buyers with room in their budget and stable income who can absorb another hike or two.
- Fixed suits first-time buyers stretched to qualify, and investors whose rent barely covers costs.
- A shorter fixed term (2 or 3 years) is a middle path if you expect rates to be lower at renewal, but it is a bet like any other.
Condo fees matter to qualifying. Lenders add part of your monthly fee to your housing costs when they calculate your debt ratios, so a high-fee building can reduce what you are approved for. See our notes on condo maintenance fees before you settle on a building.
Renewing a condo mortgage in late 2026
Owners who bought or refinanced in 2021 are renewing now at much higher rates. As an illustration, take a hypothetical $500,000 mortgage at 2.0% over 25 years. The payment was about $2,117 a month, and after five years the balance would be about $418,850. Renewing that balance over the remaining 20 years at 4.34% puts the payment near $2,605, an increase of about $488. At a 3.70% variable rate, about where the best variable rates sit after the hike, it would be about $2,466.
The good news is that switching lenders is easier than it used to be. Under OSFI’s minimum qualifying rate rules, a straight switch at renewal to another federally regulated lender does not require the stress test as long as the loan amount and amortization do not increase. Insured borrowers can switch without a new stress test too.
Tip: Most lenders will hold a renewal rate for 120 days before your maturity date. If your condo mortgage renews before early 2027, request offers from your current lender and at least one other now. If rates rise further you keep the held rate, and if they fall you can usually take the lower one.
What condo buyers and investors should do now
- Get a full pre-approval with a rate hold, not just an online estimate.
- Run your numbers at your rate plus 1% to make sure the purchase still works.
- If you are closing on a pre-construction unit, confirm your appraisal and financing early; our guide to the pre-construction condo appraisal gap explains why.
- Investors: compare the after-hike payment plus fees and taxes with realistic rent, not last year’s rent.
- Use our mortgage calculators to test fixed and variable scenarios side by side.
Frequently asked questions
Did the Bank of Canada raise rates on October 28, 2026?
Yes. The Bank raised its policy rate by 0.25% to 2.5%, taking effect October 29. Many economists had expected a hold after September’s weak jobs report, but higher inflation and high oil prices shifted the picture. The Bank said more hikes may be needed but that it will proceed carefully. The next decision is December 9, 2026.
Does the Bank of Canada rate affect fixed mortgage rates?
Only indirectly. Fixed rates are priced off Government of Canada bond yields, which react to expectations about inflation and future Bank decisions. That is why fixed rates rose in September and October 2026 even before the Bank raised its rate. Variable rates move directly when prime changes after a Bank decision.
What is the prime rate in Canada right now?
Prime at the big banks was 4.45%, according to the Bank of Canada’s posted rates table, unchanged since the October 2025 cut. After the October 28 hike to 2.5%, it is expected to rise to 4.70% as the big banks match the move.
Should I lock in my variable mortgage after the hike?
Locking in converts you to a fixed rate at your lender’s current fixed rate, which is still higher than most variable rates even after the hike. It makes sense if you cannot absorb higher payments or want certainty. If you have room in your budget, another possible hike may cost less than the higher fixed rate you would lock into.
Thinking about buying after the hike?
Read our look at whether now is a good time to buy a Toronto condo, browse condos for sale across Ontario, or talk to our team about buildings that fit your approved budget.
This article is general information as of October 2026, not legal, tax, mortgage or financial advice. Rules and numbers change, so confirm the details for your situation with a licensed professional.
The newest condos on the market
Fresh listings, updated every 15 minutes.
 $549,00081 collins Crescent, Brampton3 bed · 2 bath · Brampton NorthCourtesy of RE/MAX REALTY SERVICES INC.
 $640,000509 - 15 Skyridge Drive, Brampton2 bed · 2 bath · Bram EastCourtesy of RE/MAX GOLD REALTY INC.
 $659,900G309 - 10 Walder Lane, Richmond Hill2+1 bed · 3 bath · Rural Richmond HillCourtesy of KW Living Realty
 $529,000108 - 678 Line 2 Road, Niagara-on-the-Lake2 bed · 2 bath · 108 - VirgilCourtesy of RE/MAX NIAGARA REALTY LTD, BROKERAGE
 $369,900304 - 160 The Donway W, Toronto2 bed · 1 bath · Banbury-Don MillsCourtesy of RE/MAX RISE EXECUTIVES, BROKERAGE
 $599,900202 - 210 Sabina Drive, Oakville2 bed · 2 bath · 1008 - GO GlenorchyCourtesy of ROYAL LEPAGE REAL ESTATE SERVICES LTD.